
Market Commentary – September 14, 2026
Last week, stocks finished lower in a holiday-shortened week as higher oil prices, rising interest rates, and renewed inflation concerns pressured both equity and fixed income markets.
The S&P 500 Index fell 0.8%, while the Russell 2000 small cap index declined 2.4%, reflecting the pressure of higher long-term interest rates. West Texas Intermediate (WTI) crude oil settled near $100 a barrel as the war with Iran tightened global oil supply. Diesel prices hit a record at $6.20. The 10-year Treasury yield closed near 5%, the highest since October 2023. That move followed Friday’s Consumer Price Index (CPI) report, which came in slightly higher than expected, pushing the probability of a 25-basis-point rate hike at this Wednesday’s Federal Open Market Committee (FOMC) meeting to 88%. We believe the markets will view a rate hike by the Federal Reserve (Fed) as a positive and give the Fed greater credibility in its commitment to fighting inflation. At the same time, Oracle Corporation’s (ORCL) earnings report showed that demand for artificial intelligence (AI) infrastructure remains very strong.
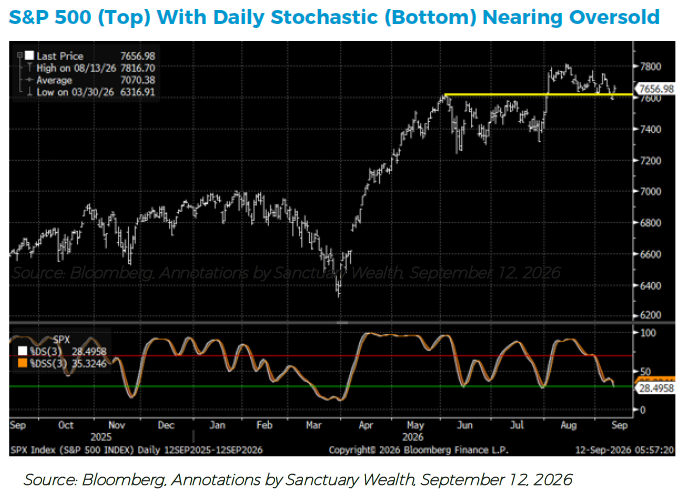
The S&P 500 has been oversold on a daily basis. This could be a sign that equities can rally on good news and would be counter to the historical decline that takes place in September — the 5-year average is a decline of 2.68%.
Keep reading:
 Loading...

 Reload document
 Open in new tab